XXXX (Company Name)

Pension Fund Strategy Workshop

As a reminder of the workshop, please refer to the following information.

Three Key Messages

1. GOAL BASED FINANCIAL PLANNING

This is often used by Financial Advisers. If you have a target, you are more likely to achieve the future lifestyle and income you want:

It can also help people feel more in control of their financial future as there is clarity on what should be planned for. You may wish to create a ‘Stretch Plan’ (along with Financial Advice potentially), however keeping the ‘simple’ objective of the programme, we suggest starting with the ‘Base Plan’, so that you can plan to meet your financial commitments.

2. ASSESS YOUR ATTITUDE TO RISK

The next step is to decide on the level of risk that you want to take.

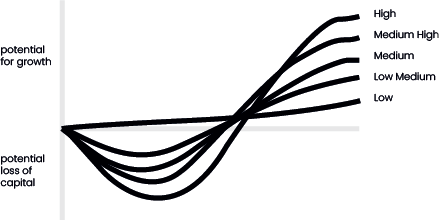
Some people want the higher risk for the capital growth potential, whereas some do not like the ‘journey’ of the ups and downs of the stock market and opt for a lower risk profile.

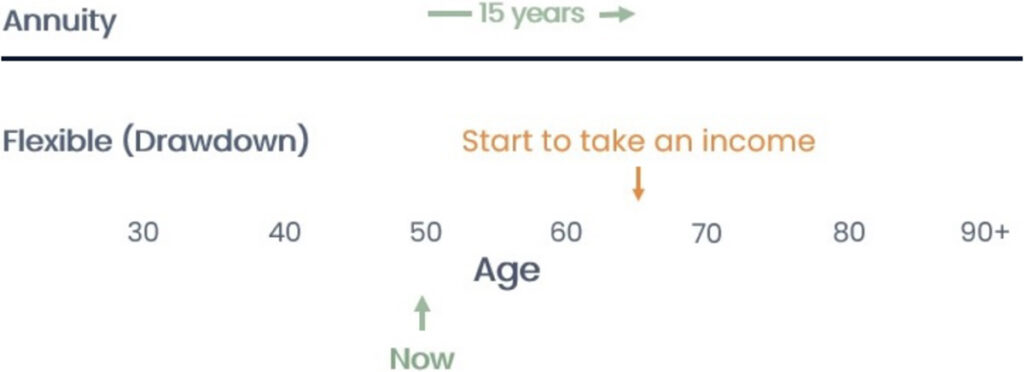
As per the previous step, a very important factor to consider here is the investment timeframe.

3. HOW MUCH INVOLVEMENT YOU WANT IN CHOOSING THE INVESTMENT FUNDS

Once you have decided on your Benefit Target and assessed your Attitude to Risk, you can then make a decision as to whether you wish to choose your own funds, from the 160 + funds that Royal London has (High involvement), or whether you want to leave this to Royal London to build a Portfolio for you (Low involvement). 

Many Royal London Portfolios (not all), have a Lifestyle strategy where the funds go into a phasing stage as retirement approached e.g. as shown below where the purple is Cash and the orange is Equities (stock market), for a client that is Targeting the Cash option. 

The current Default Fund for Piroto Labelling Limited is the ‘Balanced Lifestyle Strategy (Drawdown). You will be auto enrolled into the Piroto Labelling Default Fund, to save you making an investment choice when joining the scheme. The Default Fund changes for new joiners periodically, so you should check with Royal London as to the fund that you were invested into when the plan was set up. Whichever Default Fund you were invested in, you can switch to another fund or Royal London portfolio. We looked at three main options depending on the involvement that you want:

Low

Stay in the Default Fund

Medium

Lifestyle Strategy

High

Choose your own individual fund(s)

The links for the Medium and High options can be found on the previous page.

As regards the Lifestyle Strategies, please note that there are two additional options for each risk category (Cautious/Moderately Cautious/Balanced/Moderately Adventurous/Adventurous):

Active

Aim to outperform the market index by employing fund managers and research teams to make tactical decisions on which stocks or sectors to invest in. They tend to have higher charges than tracker funds in line with the extra resource required to run these funds. It should be remembered that a higher charge does not guarantee better returns (Source: Royal London website).

Tracker

Also known as passive funds, aim to perform in line with a market index such as the FTSE All Share index. They do this by investing in either all (full replication) or a representation (partial replication) of the index constituents. Tracker funds tend to be low cost as this replication is generally done automatically and does not require the same level of research as active management (Source: Royal London website).

The workshop focuses on the ‘standard’ option i.e. neither the Active or Tracker option. This is purely for simplicity, as we are in a workshop situation, and is not a recommendation not to use either the Active or Tracker option. You may wish to speak to Please check with (PROVIDER NAME) whether using their Transfer Service is on a Guidance (non advised) or an Advice basis. if you are considering these options.

The value of the pension will be directly linked to the performance of the funds you select and the value can therefore go down as well as up. You may get back less than you invested.