As a reminder of the workshop, please refer to the following information.
Three Key Messages
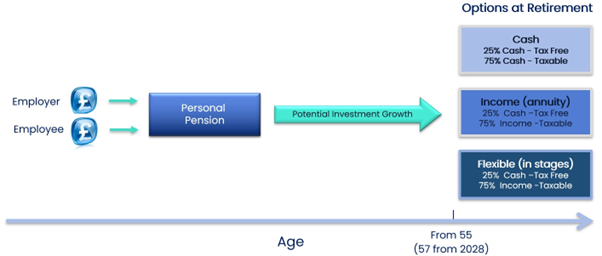
1. HOW THE SCHEME WORKS
2. CREATING A FINANCIAL PLAN
We believe in using Goal Based Planning. This is often used by Financial Advisers. If you have a target, you are more likely to achieve the future lifestyle and income you want:
It can also help people feel more in control of their financial future as there is clarity on what should be planned for. You may wish to create a ‘Stretch Plan’ (along with Financial Advice potentially), however keeping the ‘simple’ objective of the programme, we suggest starting with the ‘Base Plan’, so that you can plan to meet your financial commitments.
STRETCH PLAN
Early retirement, holiday home, cars, etc.
BASE PLAN - SAFETY
Able to meet financial commitments, bills, food, water…
Feeling of control
Knowing what to expect
Will be OK
Happier – today
STRETCH PLAN
Early retirement, holiday home, cars, etc.
BASE PLAN - SAFETY
Able to meet financial commitments, bills, food, water…
Feeling of control
Knowing what to expect
Will be OK
Happier – today
So many employees struggle to decide on what income they may need in the future, and, as a result, do not start the planning process. So the guidance is to base your plan on your outgoings today, so that you can then review this every year, if and when your circumstances change.
But then include at least one outgoing that is really important to you
Part of Financial Wellbeing can include an understanding of what makes us happy and having financial goals to achieve that happiness. This could be being a member of a sports club or being able to spend a week at your favourite holiday location
Now that you have decided on your targets, there is some excellent software to help you create your plan. It is critical though to have decided on this first, as this will mean far more to you when running through the steps on-line, than doing this without a target.
Please click here to access the Aviva Retirement Planner.
3. ALIGN YOUR RISK PROFILE TO YOUR CAPITAL GROWTH POTENTIAL
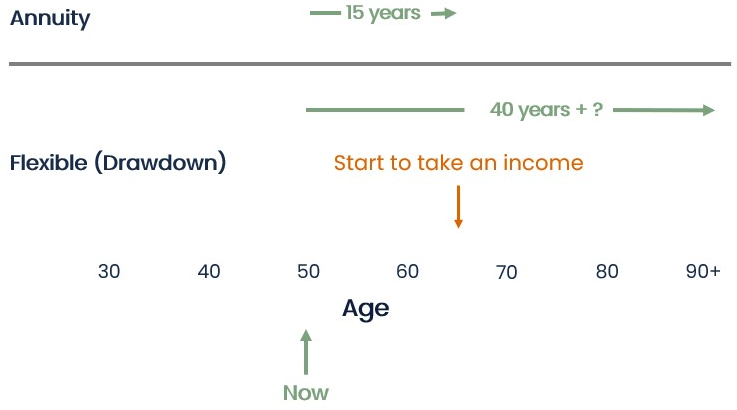
A good first step could be to decide on the Target Benefit option that you plan to take (i.e. Cash / Annuity / Flexible), as discussed in the previous section. The reason for this is the ‘timing’ of when you take the benefits:
If you are going to purchase an Annuity, this is a ‘one off’ event, so you may wish to have a lower risk profile during the years leading up to when you will do this. This is because a significant fall in the value in the year you are purchasing the Annuity, will have a significant impact on the income. Whereas, if you are going to take the Flexible (Drawdown) option, your investment timeframe may be significantly longer i.e. more time for the markets to fall and then recover.
If you want further information in respect of each option, maybe as you approach the time when you want to start taking the benefits, then please register for the ‘Pension Benefit Options’ workshop.
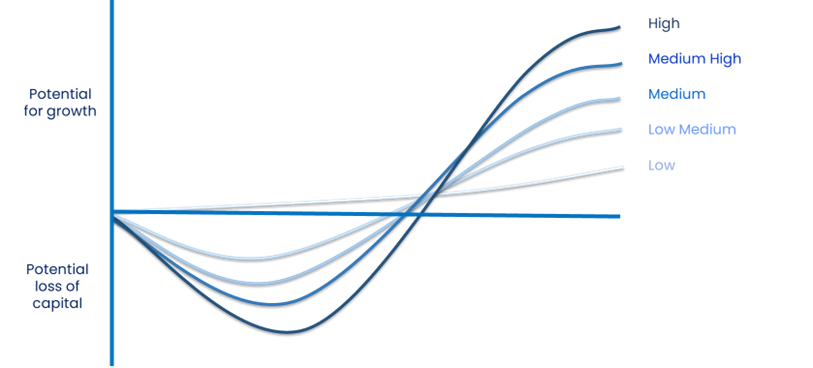
The next step is to decide on the level of risk that you want to take.
Some people want the higher risk for the capital growth potential, whereas some do not like the ‘journey’ of the ups and downs of the stock market and opt for a lower risk profile.
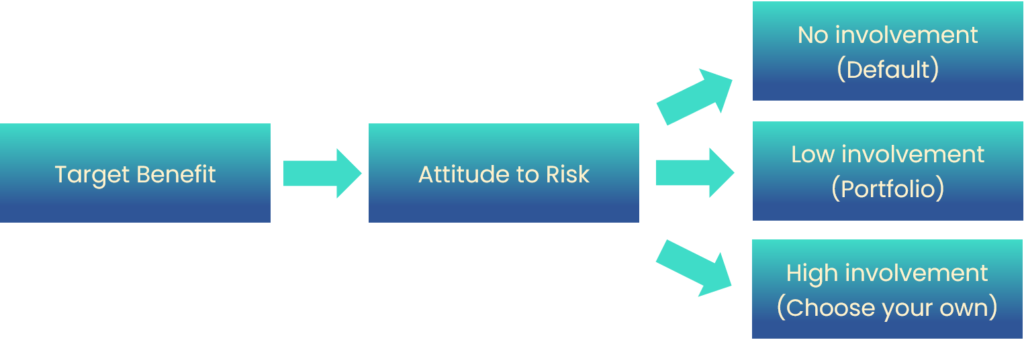
Once you have decided on your Benefit Target and assessed your Attitude to Risk, you can then make a decision as to whether you wish to choose your own funds, from the 160+ funds that Aegon has (High involvement), or whether you want to leave this to Aegon to build a Portfolio for you (Low involvement).
Many Aegon Portfolios (not all), have a Lifestyle strategy where the funds go into a phasing stage as retirement approaches.
The ‘Pension Optimiser Workshop’ will focus on the period leading up to when Lifestyling starts. This is because, during this time, it is the same investment fund, until the phasing starts, whatever the Benefit Target option is (Cash / Annuity / Flexible). You should check with Aegon when the phasing starts, and if you are approaching this date, you should consider attending the ‘Pension Benefit Options’ workshop, as it becomes more important, at that stage, to consider what Benefit Option you wish to take, and align your Investment Strategy with this target.
You will be auto enrolled into the Default Fund. This fund will be discussed during the Workshop. It changes for new joiners periodically, so you should check with Aegon as to the fund that you were invested into when the plan was set up. Whichever Default Fund you were invested in, you can switch to another fund or Aegon Portfolio. We looked at three main options depending on the level of involvement that you want:
None
Stay in the Default Fund
Low
Pension Provider Portfolio – including the Workplace Targeted Funds
High
Choose your own individual fund (s)
So, in summary:
The links for the Low and High options can be found on the ‘Pension Optimiser Workshop’ page
The value of the pension will be directly linked to the performance of the funds you select and the value can therefore go down as well as up. You may get back less than you invested. The levels and bases of taxation, and reliefs from taxation, can change at any time. The value of any tax relief depends on individual circumstances.