Pension Benefit Options Workshop
1. REVIEW THE DIFFERENT OPTIONS AS TO HOW YOU CAN TAKE THE BENEFITS

Cash
Depending on your plan, it may be possible to take all of your pension fund as Cash. 25% is tax-free and the remainder is taxed at your highest marginal rate. When this option became available, there was interest from investors that wanted to ‘take the tax hit’ and purchase a property and then rent it out (‘Buy to let’).

Annuities
There are many different types of annuity, but generally, they all pay a fixed or increasing income for life. The decision is irreversible – there is no opportunity to transfer to a different type of product if your needs change in the future. Annuity rates change regularly depending on a number of factors and can fall or rise. When an Annuity is selected, it is calculated at a single point in time – it does not allow for changing circumstances. Nevertheless, an Annuity is the only way to protect against longevity because income is guaranteed regardless of how long you live.

Flexible (Drawdown)
Drawdown is where you leave your pension pot invested and take an income directly from it. This aims to mitigate the shortcomings of an Annuity, by allowing access to an unrestricted flexible income, whilst maintaining market exposure. Drawdown requires individuals to generate a potentially rising level of income using assets whose returns can be unpredictable. Careful planning is therefore required, so that you can enjoy your retirement, but also ensure your fund does not run out.

Combination
It is possible to arrange one or more of the above.
`Income drawdown’ will reduce the size of your pension fund and the investment growth may not be sufficient to maintain the level of income you wish to draw. If you withdraw money at a rate greater than the growth achieved by your investments, your remaining fund will reduce in value. The level of income you take will need to be reviewed if the fund becomes too small – this is more likely the higher the level of income you take.
The income you receive may be lower than the amount you could receive from an annuity, depending on the performance of your investments. As annuity rates can change substantially and rapidly, there is no guarantee that when you do purchase an annuity the rates will be favourable. This could mean that your pension thereafter may be less than you hoped for. The rules governing how much income you can take directly from your pension fund may change. This could mean that the income you can take from the investment no longer meets your requirements.
2. ALIGN YOUR BENEFIT OPTION TO YOUR INVESTMENT STRATEGY
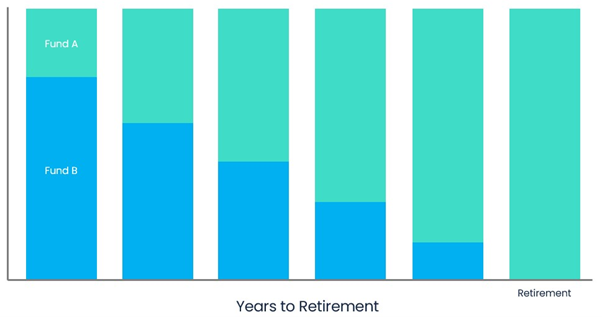
The ‘Pension Optimiser Workshop’ discussed that many Portfolios (including Default Funds) start phasing at a point in time as the time when benefits are going to be taken approaches (often known as ‘Lifestyling’). Having decided on this (previous section), you should now ensure that the Portfolio that you are invested in is targeting this option i.e. if you intend to take the Flexible option, you should be in a Portfolio that is targeting this (and hence may have a greater weighting in equities, as opposed to if you are purchasing an Annuity).
The links for other Portfolios that may be appropriate are included at the bottom of the ‘Pension Optimiser Workshop’ section.
3. REVIEW YOUR FINANCES
The ‘Pension Optimiser Workshop’ includes a review of your monthly outgoings and deciding on the income that you may need when you start taking your pension benefits. Another important aspect to consider are your Capital v Income requirements. This can impact on the level of Tax Free Cash that you may take when you start to draw the benefits from your pension plan e.g. mortgage, purchasing a holiday home etc?
When deciding on this, it is important to understand the option of taking lump sums, as and when, should you decide to take the Flexible (Drawdown) option, along with Crystalised v Uncrystallised. If you have no immediate Capital / Cash requirements, through the Flexible option, you can decide each year how much you need. This is recommended, as opposed to what some planholders have decided, which is to Crystalise the entire fund, just to have the Tax Free Cash sitting in the bank. Whereas by only taking what is required, the Uncrystallised Fund will still be invested, and then 25% of that figure may be taken as Tax Free Cash.
Uncrystalised
Before the benefit is taken
Think: 25% Tax Free
Taxable
25% Tax Free
Crystalised
After the benefit is taken
Think: Taxable
Taxable
The levels and bases of taxation, and reliefs from taxation, can change at any time. The value of any tax relief depends on individual circumstances.